|


S&P Cuts AAA Ratings on Thousands of Municipal Bonds After U.S. DowngradeBy Sarah Frier and Michelle KaskeBloomberg Aug. 09, 2011 |
Popular 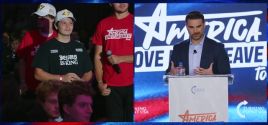
Ben Shapiro Pushes Noahide Laws at TPUSA Event, Throws a Fit Over Being Quoted Word-For-Word
From Aid to Dependency: Israeli Agent Reveals the Real Goal of 'Merging' U.S. and Israeli Militaries
ADL, Jewish Groups Lobby California to Classify Jews as a Race, 'Not Just a Faith'
Trump Welcomes 'The Highly Respected' Alan Dershowitz Into The GOP, Shills His New Book
House Passes NDAA With Section 219 Aimed at 'Merging' U.S. and Israeli Militaries

|
 Standard & Poor’s lowered the AAA ratings of thousands of municipal bonds tied to the federal government, including housing securities and debt backed by leases, following its Aug. 5 downgrade of the U.S. The rating company assigned AA+ scores to securities in the $2.9 trillion municipal bond market including school- construction bonds in Irving, Texas; debt backed by a federal lease in Miami; and a bond series for multifamily housing in Oceanside, California. Olayinka Fadahunsi, an S&P spokesman, said he couldn’t provide a dollar figure on the affected debt. S&P also cut ratings on securities backed by Fannie Mae and Freddie Mac, prerefunded issues and munis repaid by using federal assets, also known as defeased or escrow bonds. No state general-obligation ratings were affected and the company said some may remain unchanged. “It’s expected, but nobody is happy about it,” Bud Byrnes, chief executive officer of Encino, California-based RH Investment Corp., said in a telephone interview. “No one that I know thinks it was justified to cut the U.S. bonds to AA+. Once that happened, you knew that any prerefunded bonds or escrowed bonds would be downgraded too. It’s a domino effect.” Read More |